


Solid batteries – technical challenges and market trends


Solid batteries can be categorized into liquid batteries, semi-solid batteries, quasi-solid batteries and all-solid batteries according to the content of liquid electrolyte, of which the semi-solid, quasi-solid and all-solid three are collectively known as solid batteries.
Currently, the mainstream lithium batteries in the market use electrolyte as the transmission carrier, and under abnormal conditions such as overcharging and internal short circuit, the electrolyte is very prone to heat, decomposition, and flatulence, which will lead to battery combustion or even explosion.
If the liquid electrolyte is replaced with solid electrolyte, it can solve the safety problem of lithium battery from the root, and also meet the market demand for higher battery energy density and better performance.

It is understood that the current industry discussion of solid batteries generally refers to the electrolyte content reduced to 5% -15% of the semi-solid state battery, quasi-solid state battery or solid-liquid hybrid batteries, retaining some of the liquid electrolyte, so that it has the feasibility of mass production in the design of the material, manufacturing process, equipment production, cost and other aspects.
“Relying on a strong new energy industry chain manufacturing base, Chinese battery companies have made important breakthroughs in solid state battery technology research and development, industry chain layout, especially along with the mass production of semi-solid batteries loaded with major battery manufacturer giants as the representative of Chinese companies, semi-solid batteries have truly achieved industrialization in the sense of economics.”
In the recently held 2024 Solid State Battery Industry Ecosystem Entrepreneurs Summit, experts pointed out that the commercial application of solid state batteries is approaching, who first occupies the industrial high ground, who will be able to grasp the initiative of development.
Although semi-solid batteries have achieved large-scale mass production and applications, the commercialization of all-solid batteries still faces a series of challenges, including technology and cost.
Solid electrolyte to replace liquid electrolyte, the core of its technology is the choice of materials, the industry has explored three main types of solid battery system: polymer, sulfide, oxide.
Solid polymer electrolyte is easy to process, dry and wet manufacturing processes are compatible, the mass production process is the least difficult, but the conductivity is low, European companies focus on this technology route.
Sulfide performance is the best, but the material is sensitive to moisture in the air and most of the polar solvents, and the manufacturing of battery cells need to be isostatic pressure equipment to apply pressure, the cost is high, CATL, BYD, EVE focus on this technology route. Some startups are choosing the oxide technology route.
All-solid battery is an innovative upgrade of materials, cell manufacturing process, manufacturing equipment and other aspects, and the industry chain will usher in revolutionary changes(Explore the lithium battery manufacturing process).

At present, solid battery applications have challenges in system design and recycling. For example, in the manufacturing process, liquid batteries have a diaphragm, which can be wrapped around the pole pieces to avoid short circuits caused by misalignment between the pole pieces, and do not require ultra-high pressure densification;
While solid batteries do not have a diaphragm, layers are stacked up to be densified by ultra-high pressure, and the edges of the pole pieces are prone to breakage and misalignment, and it is very difficult to solve the insulating process on the side of the electric core.
Solid batteries are like burgers, stacked one on top of the other, the vegetables inside will be exposed from the edges, and are prone to rupture after extrusion, resulting in short circuits. And liquid batteries are like pancakes rolled vegetables, is wrapped up, will not short circuit.
At present, the cost of solid batteries is higher than liquid batteries. A professional example: “sulfide solid electrolyte material costs are very high, up to $2750 per kilogram, the future cost is expected to drop to $690/kg, while the solid electrolyte accounted for the proportion of the quality of the battery core is more than 20%, I am afraid that the market is difficult to accept this price.”
As the technical route and cost reduction space are still unclear, companies in the industry have chosen to gradually transition from semi-solid state to all-solid.
“The all-solid battery route is divergent, and differentiated competition will prompt solid batteries to expand the scope of application.” In the view of industry insiders, at present, a single solid electrolyte material is difficult to meet the demand for all-solid batteries, the combination of liquid electrolyte and solid electrolyte is a solution to make up for the shortcomings of a single electrolyte material at the same time, compatible with most of the traditional liquid lithium batteries process equipment, reduce costs.
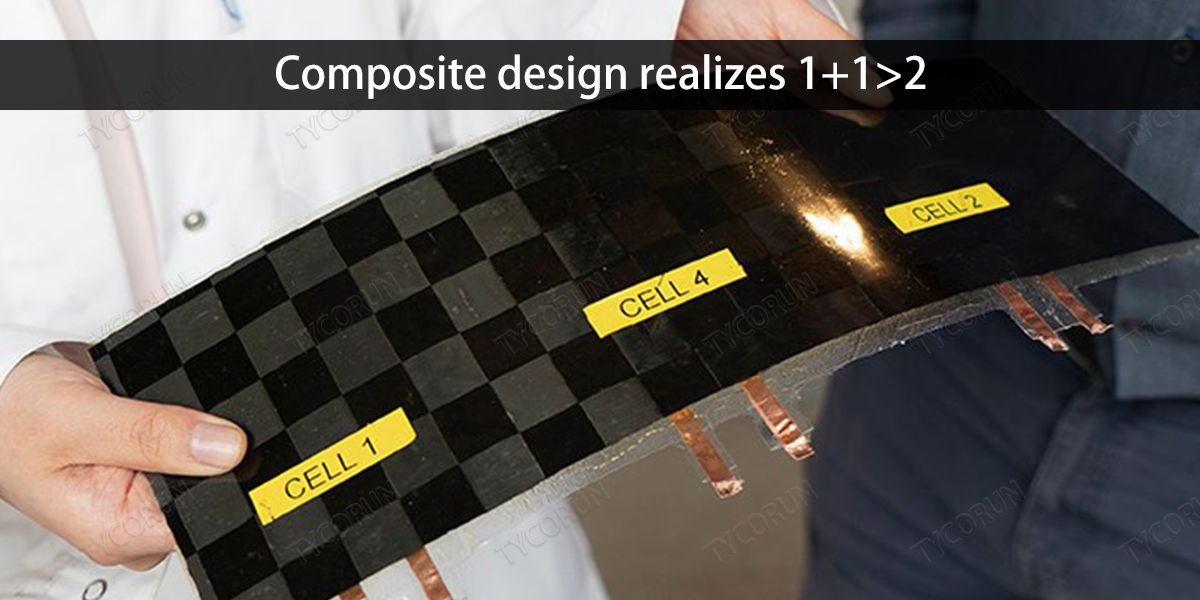
“A single type of material has its own advantages and disadvantages, and 1+1>2 can be realized through composite material design,” an industry insider similarly believes that composite solid batteries are an effective way to achieve large-scale mass production. “solid batteries can’t be made into a work of art, the product is very expensive, a few times or even a dozen times higher than liquid batteries, so that they can never be installed in vehicles and applied.”
Whether semi-solid or all-solid, there is the most suitable energy density, there is no one type of technology is the only optimal solution, are the solution to the demand for high specific energy under the safety hazards of the battery cell the same technical means. Tackling the technology and industrialization of all-solid batteries requires the joint efforts of the whole industry.
Solid battery technology is considered to be the key to breaking through the upper limit of lithium-ion battery energy density, especially in the field of revolutionary electric vehicles(solid state ev batteries).
With the growing demand for new energy vehicles and increasing market share, solid batteries will become the ultimate direction for lithium-ion battery development.
However, given the technical and cost challenges, the road to full commercialization of all-solid batteries is still long. Liquid batteries will remain mainstream in EV applications for some time to come.

According to EVTank’s forecast, by 2030, about 90% of the global lithium battery market will still be traditional liquid batteries, with the remaining about 10% being solid batteries. Of the market share occupied by solid batteries, the majority will belong to semi-solid batteries.
The development of solid batteries is promising, but its commercialization process still needs to overcome many challenges.
With the discovery of new materials, advances in manufacturing technology, and strengthened policy support, solid batteries are expected to be widely used in a number of fields, contributing to solving the energy crisis and realizing sustainable development. The arrival of solid batteries may be faster than we expected.
Read more: top 10 lithium battery electrolyte manufacturers.


Leave a comment